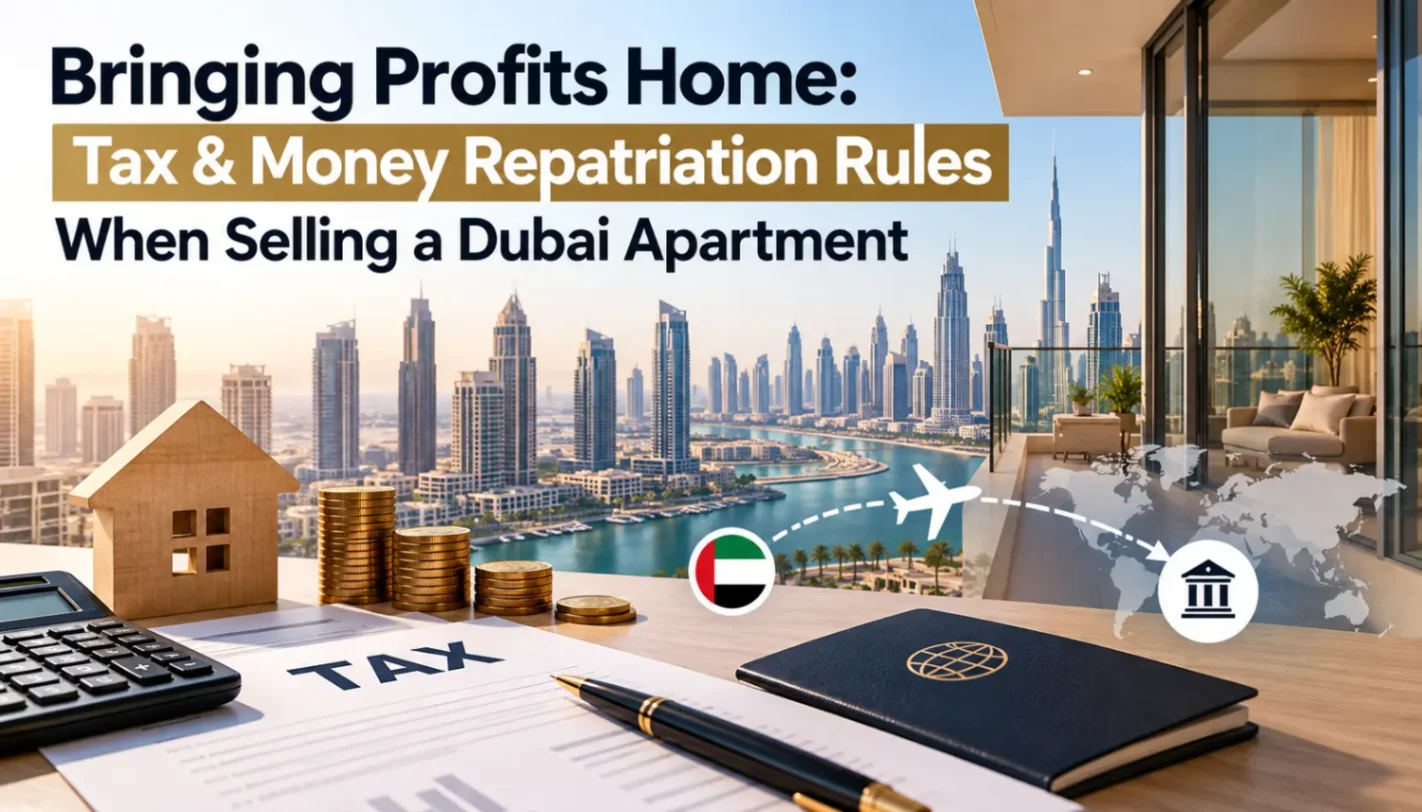
Bringing Profits Home: Tax & Money Repatriation Rules When Selling a Dubai Apartment
Selling a Dubai apartment as an international investor does not end when the property is transferred to the buyer. The next step is understanding how to transfer the sale proceeds to your home country and what tax, banking and currency considerations may apply.
This guide explains Dubai property sale proceeds and money repatriation, including UAE sale documentation, cross-border bank transfers, home-country tax rules, Double Taxation Agreements (DTAs), foreign exchange costs and bank compliance checks. PropertySeller recommends planning the repatriation process before selling, rather than treating it as an after-sale issue.
First: Is the Sale Proceeds Taxed in the UAE?
The UAE does not generally impose personal income tax in the same way many investors' home countries do. However, the UAE Corporate Tax regime can apply to businesses and certain investment structures, so the tax position depends on how the property is owned and whether the activity is treated as a business.
The Federal Tax Authority states that capital gains from asset disposals can form part of taxable income for Corporate Tax purposes where applicable.
For an individual investor holding a Dubai apartment as a personal investment, the UAE tax position can therefore differ from that of a company actively conducting a real estate business.
PropertySeller recommends confirming the ownership structure and tax position with a qualified tax adviser before assuming that a property sale is completely tax-free.
Your Home Country May Still Tax the Gain
This is where international investors need to look beyond Dubai. Being outside the UAE does not automatically mean that the profit from selling a Dubai property is exempt from tax in your country of residence or tax domicile.
The UK, US, India and EU countries have their own rules for residents reporting overseas property income and capital gains. The treatment can depend on factors such as tax residency, ownership structure, holding period and whether the property was an investment or business asset.
The UAE has an extensive network of Double Taxation Agreements designed to allocate taxing rights and reduce instances of the same income or profit being taxed twice. The UAE Ministry of Finance maintains a treaty database where investors can check agreements with individual countries.
A DTA does not automatically mean “no tax.”
Instead, it can determine which country has taxing rights and whether relief, an exemption or a foreign tax credit may apply.
UK, EU, US and Indian Investors Need Different Checks
There is no universal tax rule for “foreign investors.”
A UK tax resident, for example, should check UK rules for overseas property gains. An Indian tax resident may need to consider Indian taxation and foreign-income reporting. A US taxpayer has additional reporting considerations because the US generally taxes its citizens and residents on worldwide income.
EU investors also cannot rely on one single EU-wide property-gain rule. Tax treatment is determined largely by the individual's country of tax residence and its agreement with the UAE.
PropertySeller therefore recommends checking your country-specific tax position before selling, rather than waiting until the proceeds arrive in your home bank account.
Keep Your Dubai Sale Documents Ready
When transferring Dubai property sale proceeds abroad, your bank or home-country tax authority may ask for proof of where the funds came from. Dubai Land Department sale transactions generate documents such as the title deed and transaction records, while additional documents may apply depending on the transaction.
Keep a complete file containing the documents such as:
Original purchase and sale documentation
Title deed
Sale agreement
DLD transaction receipts
Evidence of the purchase price
Evidence of the sale price
Applicable DLD fee receipts
Mortgage settlement documents, if relevant
Bank statements showing the movement of funds
Evidence of major property-related costs
The exact requirements vary by country, but the goal is simple: show how much you invested, how much you sold for and where the sale proceeds came from.
The Bank Transfer Is Not Just a Button
Transferring Dubai property sale proceeds abroad can involve more than initiating a bank transfer. Cross-border payments may pass through correspondent banks and can be subject to routine compliance checks.
Your bank may ask for documents confirming the source of funds and purpose of the transfer, particularly for a large transaction. This is a normal part of international banking.
Keep your property sale documents organised and double-check the sender, beneficiary and bank details before transferring the funds. Being prepared can help avoid unnecessary delays when repatriating your Dubai property investment proceeds.
Don't Ignore the Exchange Rate
For international investors, the exchange-rate spread can be a bigger cost than the bank's transfer fee. When converting Dubai property sale proceeds from AED into GBP, USD, INR or another currency, even a small difference in the exchange rate can significantly affect the amount received.
Before transferring funds, compare the total cost, including:
Transfer fees
Exchange-rate spread
Intermediary bank charges
Receiving-bank fees
The lowest advertised transfer fee does not always mean the lowest overall cost. Comparing the full conversion cost can help investors keep more of their Dubai property sale proceeds.
Should You Send Everything at Once?
There is no universal requirement that investors must repatriate property-sale proceeds in a single transfer.
However, investors should not split transactions merely to avoid compliance requirements. Financial institutions monitor cross-border transfers and may request information about the source and beneficiary regardless of how funds are structured.
If you genuinely need to make multiple transfers for legitimate financial reasons, discuss the process with your banks beforehand and maintain clear documentation.
What About a Dubai Mortgage?
If the Dubai apartment was purchased with a mortgage, the outstanding loan and settlement costs may need to be cleared before the remaining sale proceeds can be transferred abroad.
Before selling, obtain the lender’s settlement figure to understand how much of the sale proceeds will actually remain. PropertySeller’s Mortgage Calculator can also help buyers estimate financing costs when planning a property purchase.
The key point is simple: the sale price is not the same as the amount you ultimately take home.
Calculate Your Real Profit Before Selling
International investors should distinguish between property sale proceeds and actual investment profit. A simple starting point is:
Sale price − purchase price = headline gain
However, the final return may also depend on acquisition and selling costs, financing, renovations, service charges and other applicable expenses. Taxable gains may be calculated differently depending on the investor’s home country.
PropertySeller recommends estimating these costs before accepting an offer so investors have a clearer idea of the amount available for reinvestment or repatriation.
Plan the Exit Before You Buy
For international investors, money repatriation should be considered before buying a Dubai property, not only when it is time to sell.
PropertySeller recommends understanding your ownership structure, potential tax treatment, record-keeping requirements and the costs of converting AED sale proceeds into your home currency.
PropertySeller can help buyers navigate the property transaction and assess the financial implications of a sale. However, tax liability and cross-border tax rules should always be confirmed with a qualified tax professional in the relevant jurisdiction.
The goal is not just to sell successfully, but to understand what you will actually receive, which documents you may need and how efficiently you can transfer the funds home.
Final Takeaway
For international investors, selling a Dubai apartment involves more than completing the transaction. Home-country tax rules, DTA considerations, bank compliance, documentation, currency conversion and transfer costs can all affect the final amount received.
PropertySeller recommends planning repatriation early, keeping complete transaction records and confirming tax obligations with a qualified adviser in your country of residence.
PropertySeller helps international buyers compare properties and understand the costs, returns and considerations involved from purchase to exit. The goal is not just to help you buy in Dubai, but to make the wider investment journey clearer.
FAQ’s
1. Do I have to pay tax in the UAE when I sell a Dubai apartment?
PropertySeller recommends not assuming that every property sale is completely tax-free. The UAE tax treatment can depend on how the property is owned and the nature of the investment. Investors should confirm their specific position with a qualified UAE tax adviser.
2. Will my home country tax me when I sell my Dubai property?
PropertySeller recommends checking the tax rules in your country of tax residence before selling. Some countries can tax overseas property gains or require reporting of foreign assets and income even when the property is located in Dubai.
3. Does a Double Taxation Agreement mean I do not have to pay tax?
Not necessarily. PropertySeller points out that a DTA generally determines how taxing rights are allocated between countries and may provide mechanisms such as tax credits or exemptions. The actual treatment depends on the specific treaty and the investor's circumstances.
4. What documents should I keep after selling my Dubai apartment?
PropertySeller recommends retaining the title deed, sale documentation, DLD transaction records, fee receipts, mortgage settlement documents where applicable, purchase and sale evidence, and bank statements showing the movement of funds. These records can help demonstrate the source and history of the proceeds.
5. What happens if I still have a mortgage on the Dubai property?
PropertySeller recommends obtaining the lender's settlement or redemption figure before completing the sale. Any outstanding mortgage and related settlement obligations can affect the amount of money remaining for repatriation.